The Noise Test: Detect
Overfitting to Historical Volatility
Create 1,000 noise-adjusted price series and re-trade your strategy on each one. If profitability collapses when noise changes, the strategy was fitted to noise, not signal.
The Short Answer
The Noise Test is a robustness test for trading strategies that adds and subtracts small random amounts of volatility from historical price data to create hundreds or thousands of new price series, then re-trades the strategy on each one. If performance collapses when the noise changes, the strategy was fitted to noise rather than a real signal. David Bergstrom created the Noise Test for Build Alpha, where it has been part of the software since its launch in 2016.
Origin: I built the Noise Test, along with the Variance Test, into the first release of Build Alpha in 2016. I explained both on the Better System Trader podcast in March 2017 and wrote about the Noise Test for See It Market that June.
When Out-of-Sample Data Is Not Enough
The first line of defense against curve fitting is out-of-sample testing. But OOS alone might not be enough. There are two parts to the underlying data: the signal and the noise. When something is curve fit, it is "fitted to the noise" and does not capture the underlying signal. See how to tell if a trading strategy is overfit.
The Noise Test answers a question OOS cannot: would this strategy still work if the noise was different?
What Is the Noise Test?
The Noise Test adjusts the original price data by differing amounts (user-selected), creating hundreds or thousands of new volatility-adjusted price series. It then re-trades the strategy on each one.
The idea: if the strategy cannot produce a profit on noise-adjusted data, it was overfit to the historical noise, not capturing a real underlying signal, and unworthy of live trading.
Core Principle
Historical data is only one possible path of what could have happened. The noise, the random volatility around the signal, will always be different going forward. A robust strategy should survive when noise changes. An overfit strategy collapses.
How It Works in Build Alpha
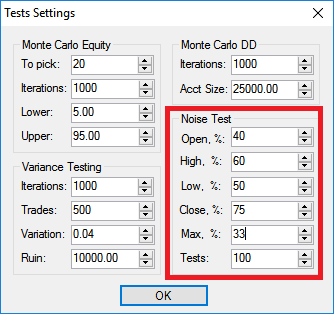
The trader configures how much data to adjust and by how much. For example: change up to 40% of the opens, 60% of the highs, 50% of the lows, and 75% of the closes, each by up to 33% of the average true range.
What Does Noise-Adjusted Data Look Like?
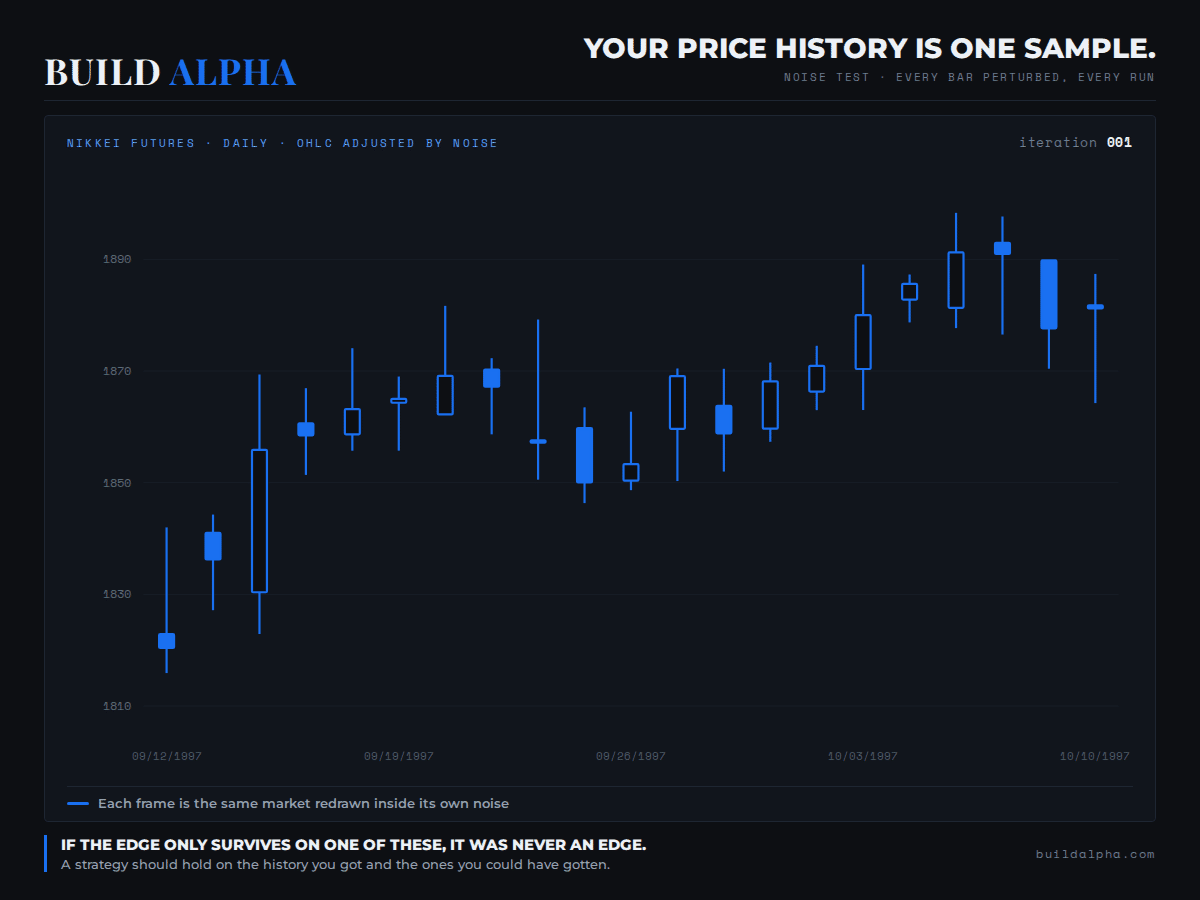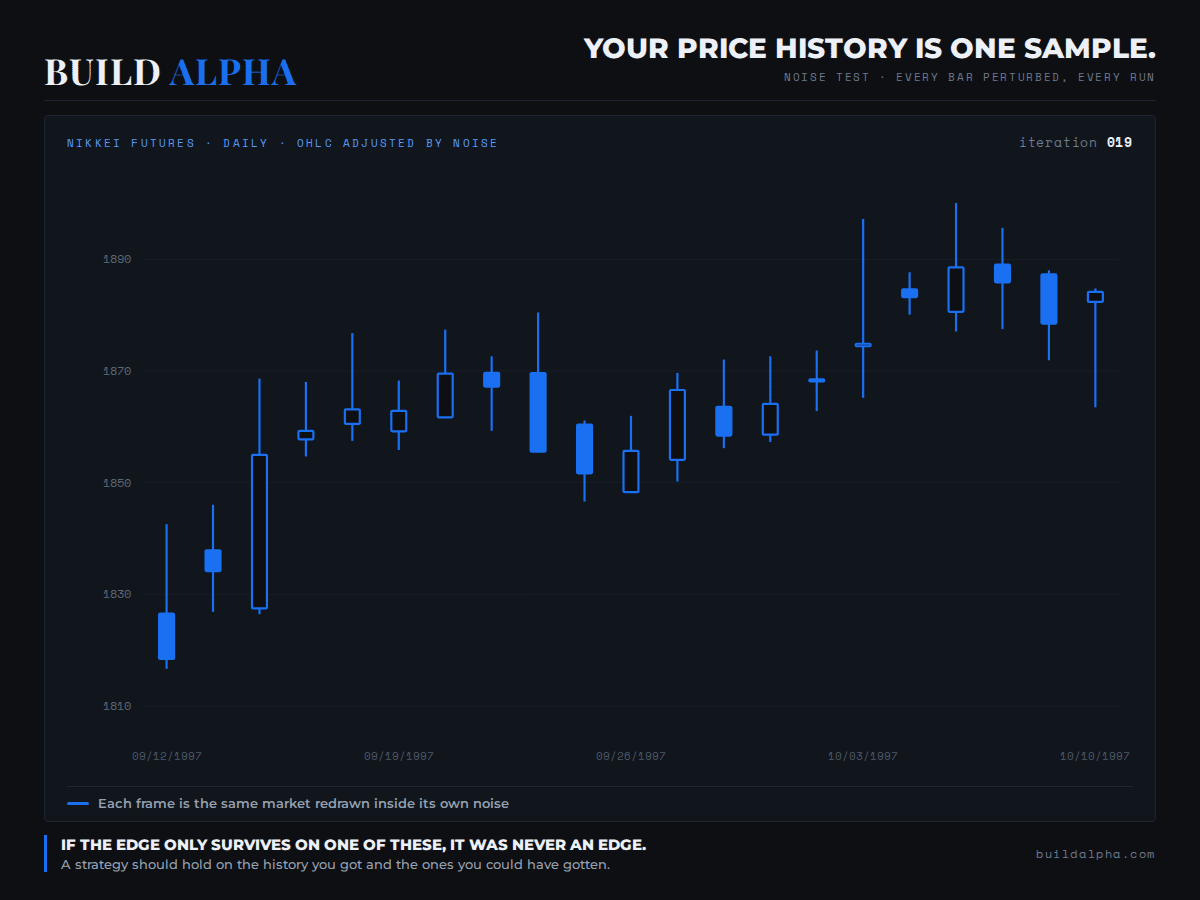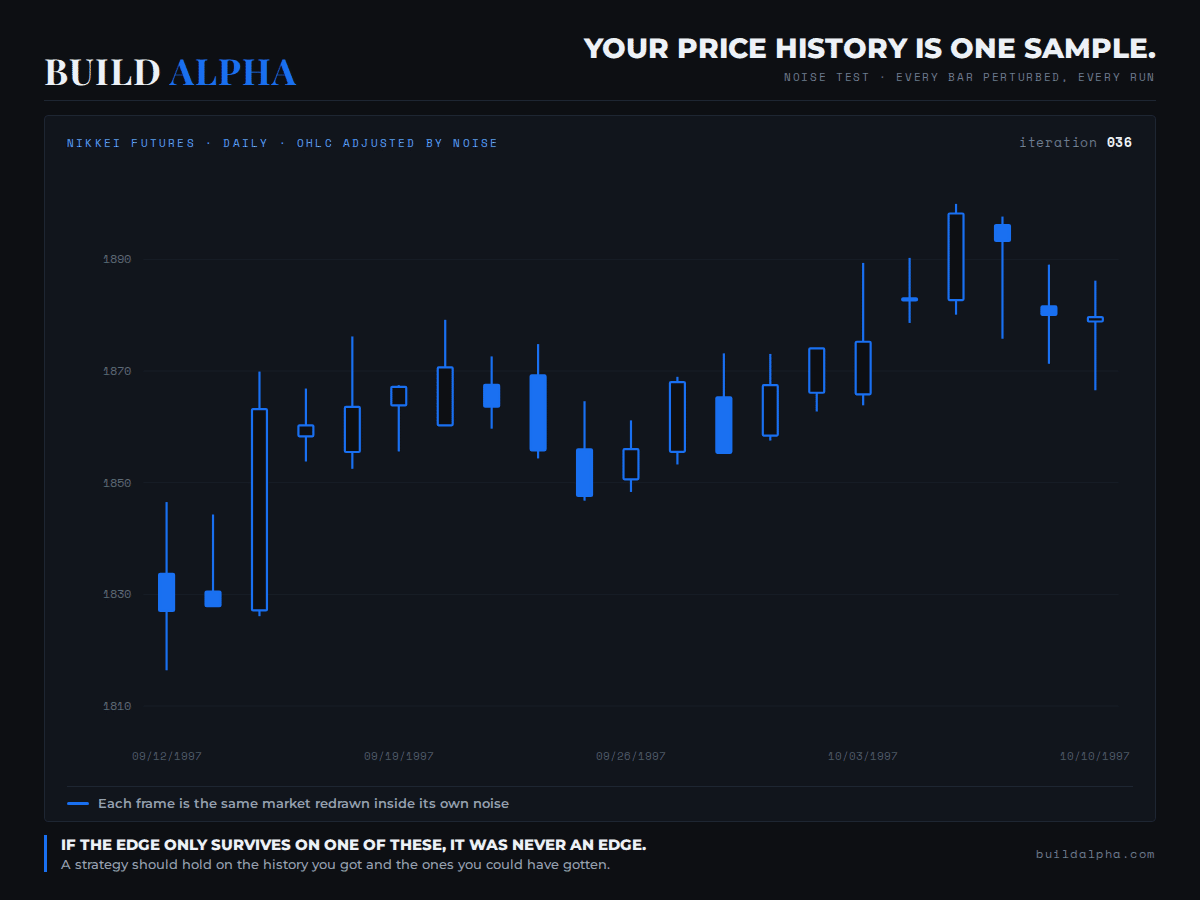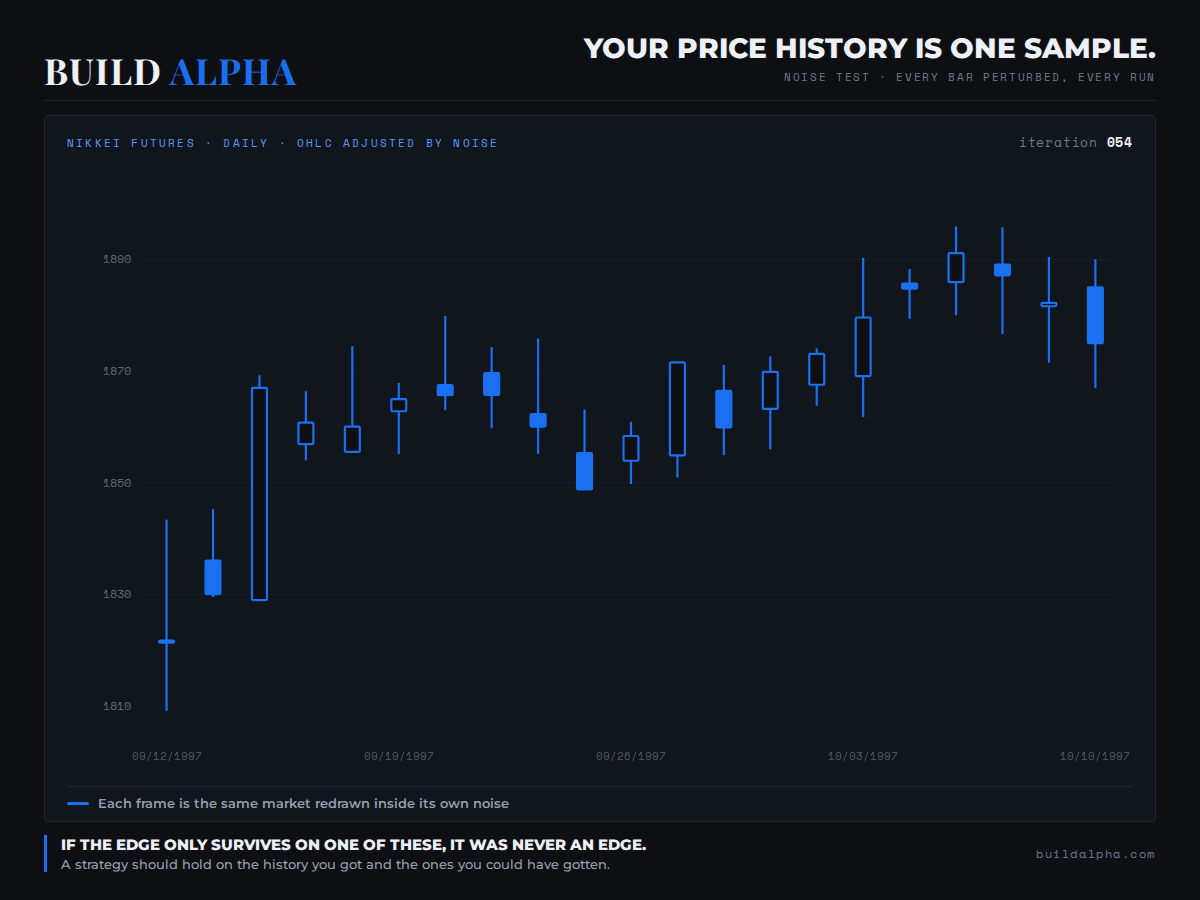
Below are four noise-altered price series for the S&P 500 during the August 2015 ETF crash. Notice how some bars have changed, some even turned positive when originally negative (and vice versa). The data still mimics the original S&P 500 and preserves characteristics like volatility clustering, but the noise is different.


Interpreting Noise Test Results
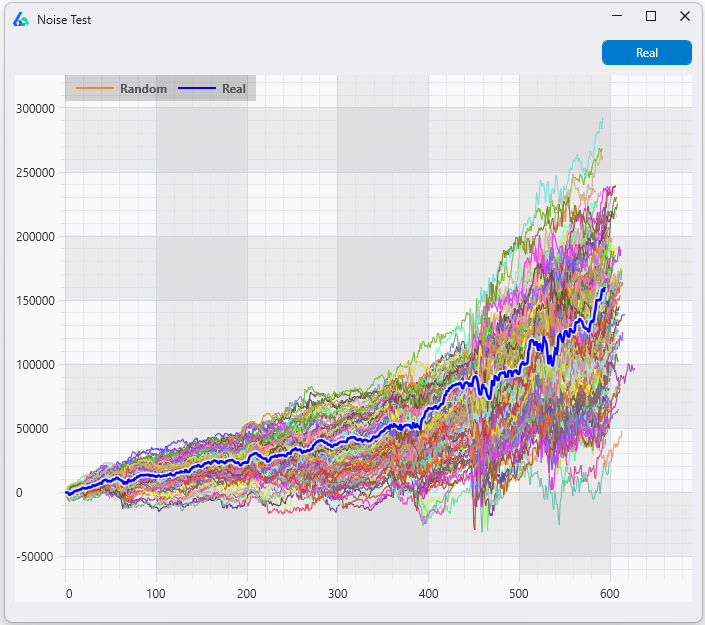
After adjusting the data, the Noise Test re-trades the strategy on each new price series and displays the resulting equity curves. The original backtest appears as a thick blue line, and you're looking at where it sits relative to the noise-adjusted distribution.
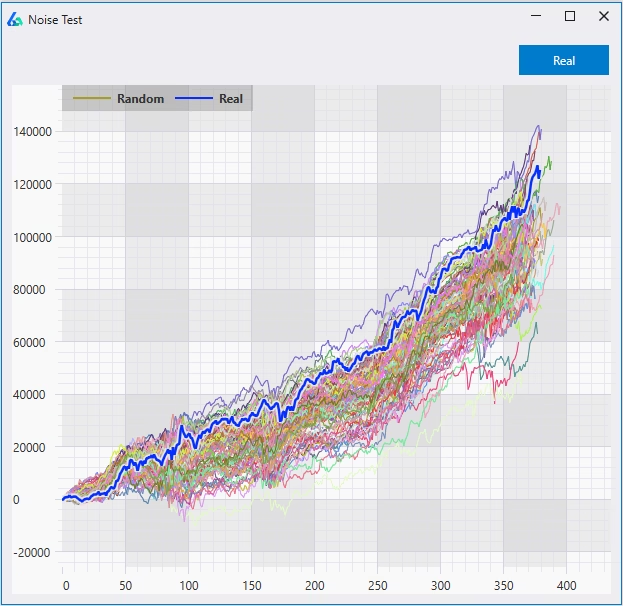
Most noise-adjusted curves remain profitable. Distribution stays meaningfully above zero. Backtest sits within the cluster.
Profitability survives but drawdowns explode or results become highly inconsistent with the backtest.
Many noise-adjusted runs cluster near zero or negative. Original backtest is a significant outlier above the spread.
Tight vs. Wide Noise Test Results
Beyond pass/fail, the spread of the noise test distribution reveals how sensitive your strategy is to noise changes. This is one of the most informative signals you can get from the test.
The noise-adjusted equity curves cluster tightly around the original backtest. Changing noise barely affects performance. The strategy is trading the underlying signal, not the noise. This is what you want to see.
Even if some curves dip, the tight cluster means the strategy's edge persists across many alternate realities.
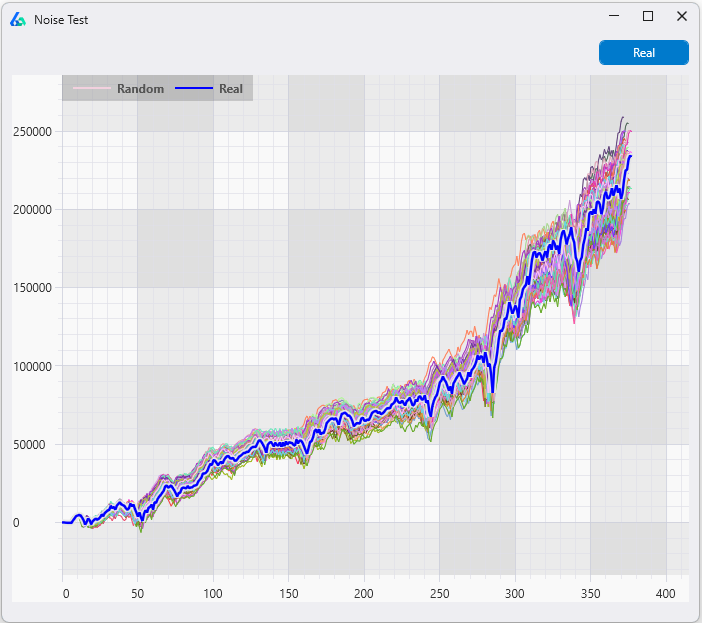
The noise-adjusted equity curves spread widely, some highly profitable, some deeply negative. Small noise changes cause massive performance swings. The strategy depends on the exact historical noise pattern.
If the original backtest sits at the top of a wide spread, it's almost certainly overfit. This is a lying backtest.
🔑 The Key Insight
A strategy with a beautiful backtest but wide noise test spread is more dangerous than a modest backtest with tight noise test spread. The wide spread means your live results could land anywhere in that distribution, and most of it is worse than your backtest. A tight spread means live results will likely resemble the backtest regardless of future noise.
What To Do When Noise Tests Fail
If your strategy fails the noise test or shows warning signs, consider these next steps:
- Simplify the strategy. Fewer rules and conditions make it harder to overfit
- Reduce parameter precision. Round to wider values (e.g., use 20 instead of 23.7)
- Add contextual filters. Market regime signals can add stability without overfitting to noise
- Run additional robustness tests. Combine with Monte Carlo simulation, Vs Random, and walk-forward analysis
- Try noise test parameter optimization. Optimize across noise-adjusted data instead of the single historical path
Noise Test Parameter Optimization
Build Alpha takes the Noise Test further: instead of just testing on noise-adjusted data, you can optimize parameters across it. This means finding parameter settings that work well not just on the one known historical price path, but across many alternate realities.
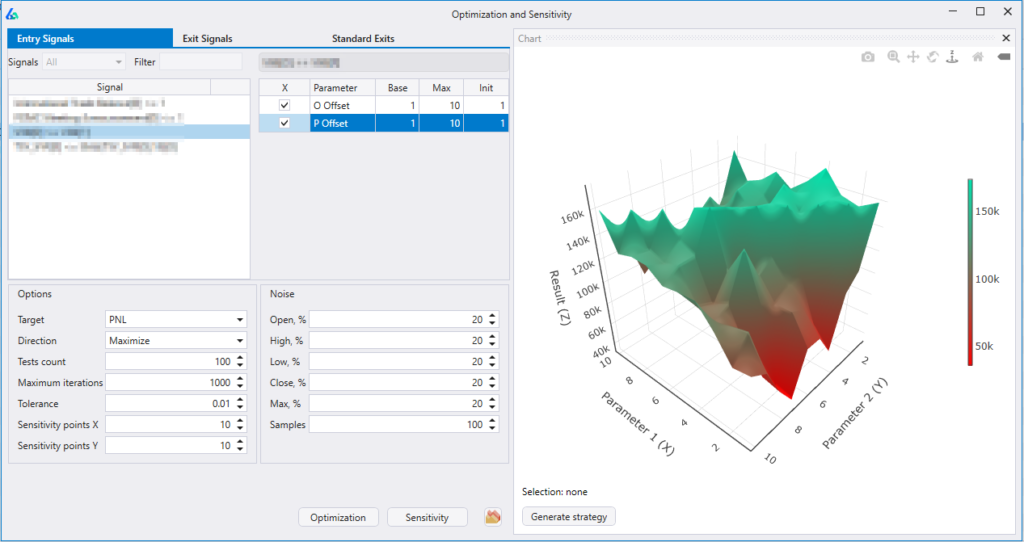
In a case study, noise test optimization returned about 33% more profit than traditional optimization over a forward test period. The full deep dive with results: Noise Test Parameter Optimization.
Noise Test in the Automated Workflow
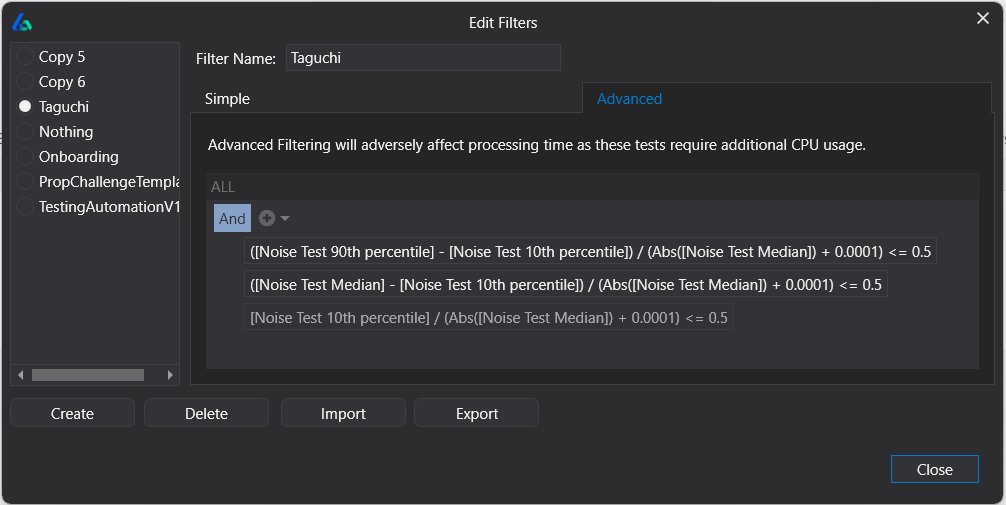
In Build Alpha v3, the Noise Test can be set as an automated pass/fail filter. Define your Noise Test threshold. Build Alpha only returns strategies that pass. No manual review of failing strategies. Combine with OOS filters, Monte Carlo, Vs Random, and more in a single pipeline.
The result: you spend time on the small number of strategies that survive everything, not sorting through noise. More on the full automated strategy generation workflow, automatic strategy generation, and building strategies on synthetic data.
Layering Taguchi filters into the same pipeline narrows the parameter search with orthogonal arrays instead of testing every combination, cutting runtime while still catching the noise-sensitive strategies the pass/fail gate is there to stop.
Watch the automated Noise Test workflow in Build Alpha
Takeaways
✓ Key Takeaways
- The Noise Test detects overfitting by perturbing historical noise and re-trading. If profitability collapses, the strategy was fitted to noise
- Tight noise test results signal robustness; wide spread signals fragility and a likely lying backtest
- Noise Test Parameter Optimization finds parameters that work across many alternate realities, not just the known past
💡 Need to Know
- Configure each OHLC component independently, control what percentage of bars to alter and by how much
- The Noise Test can be automated as a pass/fail filter in Build Alpha v3
- Combine with the full robustness testing suite, and no single test is sufficient alone
Noise Test FAQ
Related Deep Dives

David Bergstrom
A decade-plus in professional trading as a market maker and quantitative strategy developer at a high-frequency trading firm with a CME seat. Self-taught C++, C#, and Python programmer specializing in data science, machine learning, and trading strategy development.
What Traders Say About Build Alpha






Is Your Strategy Trading Signal or Noise?
1,000 noise-adjusted price series. Automated pass/fail. No coding required.